
The Federal Scholarship Tax Credit: What We Know
On October 1, 2026, Treasury and the IRS released the first rules for the new federal scholarship tax credit. These are proposed and temporary regulations, not final ones. Some details may change after public comment. But for the first time, schools have something concrete to plan around.
I've been following school choice programs as part of my work on school financial sustainability, and I'll keep this page up to date as the rules take shape. The latest changes are logged at the bottom.
What the rules spell out
The credit. Individuals who give to a scholarship-granting organization (SGO) can receive a federal tax credit of up to $1,700. Married couples filing jointly can claim up to $3,400.
When and where. The credit applies to gifts made starting January 1, 2027, and only in states that opt in.
No gifts for a particular student. Donors can't direct a gift to a specific child.
Timing of awards. SGOs have until the end of the following year to award what they raise, so some scholarships funded by 2027 gifts may not be awarded until the 2028–29 school year.
Paperwork for donors. Each donor receives a written acknowledgment from the SGO by January 31 of the following year, with a unique donor number they use to claim the credit on their federal return.
Can anyone act on proposed rules? Yes. For 2027, donors and SGOs can rely on the proposed rules even before they're final.
Where your state stands
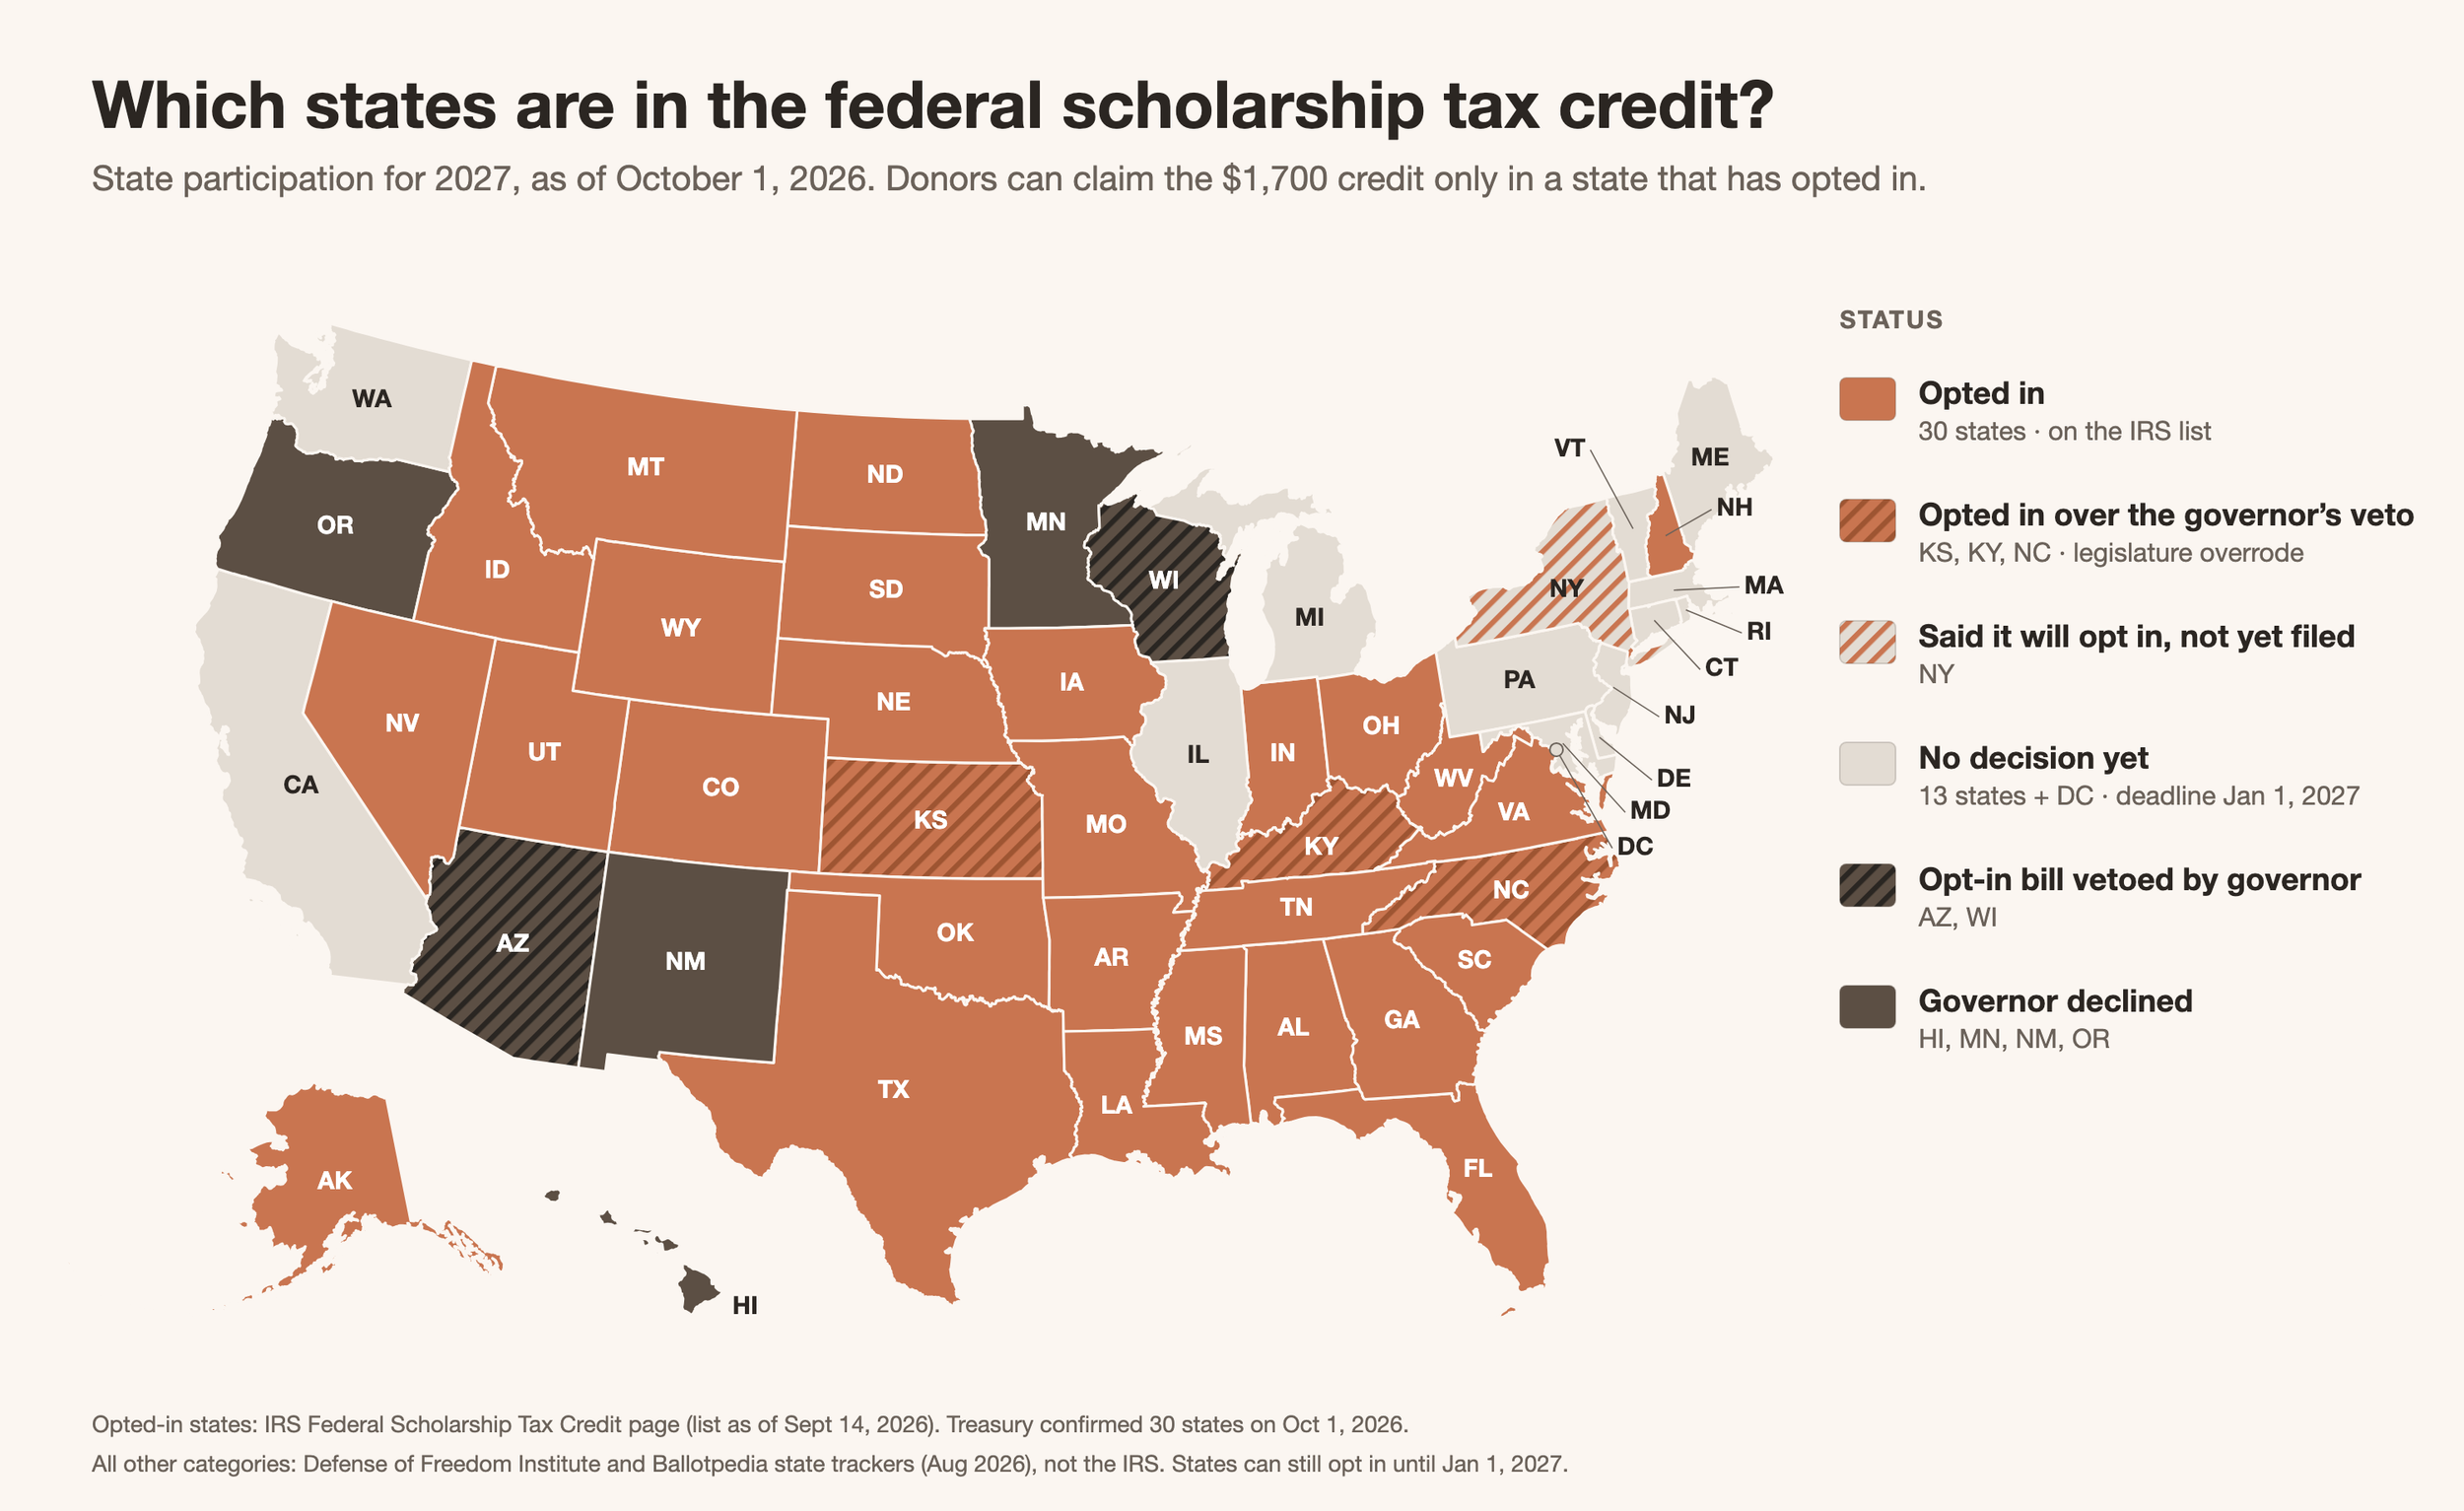
Which states are in for 2027, as of October 1, 2026. Opted-in states come from the IRS list (current as of September 14, 2026). The other categories come from public state trackers.
Thirty states have opted in so far. States have until January 1, 2027 to opt in for 2027, so this map will change. The IRS keeps the official list on its .
Dates to know
Here are the dates that shape the first year of the program:
Early December 2026: Public comments on the proposed rules close.
December 15, 2026: Public hearing on the proposed rules.
January 1, 2027: Deadline for states to opt in for 2027, and the first day a gift can earn the credit.
February 15, 2027: Deadline for each state to submit its list of approved SGOs. An SGO not on the list by then can't receive credit-eligible gifts until 2028.
January 31, 2028: SGOs send 2027 donors their acknowledgments.
In states that are new to scholarship-granting organizations, the February 15 date matters most. States review each SGO before listing it, so the practical deadline for a new SGO to start earlier.
The question still open
The question I think all of our schools are waiting to get a definitive answer to is whether a donor can direct their gift to a specific school.
The proposed rules don't yet address it. They prohibit gifts for a particular student, and they require every SGO to fund students at more than one school, so a school can't set up an SGO for itself alone. On designating a school, the rules say nothing either way. You'll see confident answers online in both directions, and neither is supported by the rules as written. This is likely to come up during public comment.
Why the advancement office feels it first
Whichever way that question goes, I expect the advancement office to feel this before anyone else.
If donors can choose a school, the credit becomes a new way for a school's own community to give, routed through an SGO instead of the annual fund. If they can't, it competes with the annual fund for the same year-end dollars, and the school has no say in where those dollars go. Either way, the credit's deadline is December 31, which lands in the middle of the season advancement offices already count on most.
What's changed
October 2, 2026. Page created.
October 1, 2026. Treasury and the IRS released the proposed and temporary rules. Thirty states are on the IRS list. The question of donors designating a school remains open.
